Why Financial Literacy Should Be Taught in Schools
In today’s rapidly changing world, education is no longer limited to textbooks, examinations, and academic achievements. Preparing students for real-life challenges is equally important. One essential life skill that often receives insufficient attention in school curricula is financial literacy. Understanding how to earn, save, spend, invest, and manage money is fundamental to leading a financially secure life. Therefore, financial literacy should be introduced in schools as an essential component of modern education.
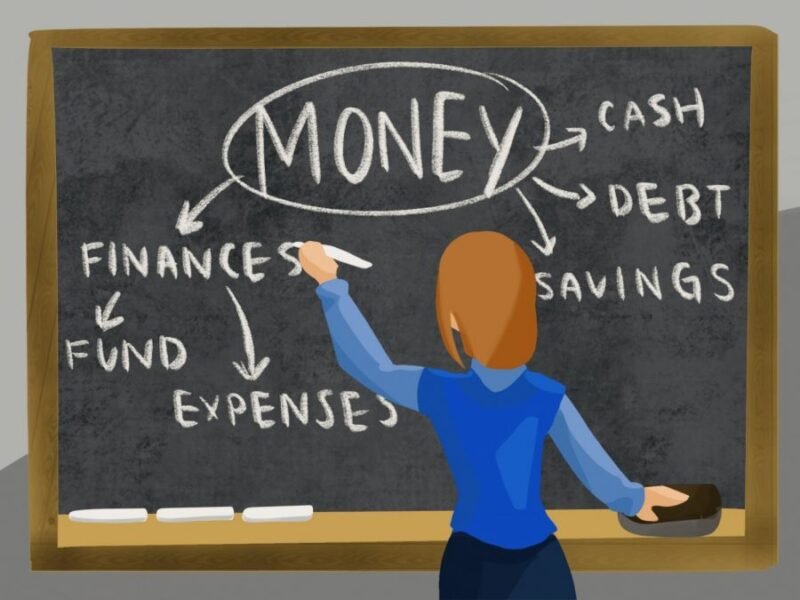
Financial literacy refers to the ability to understand and manage financial matters effectively. It includes basic knowledge of budgeting, saving, banking, interest rates, loans, investments, taxation, and digital payments. A financially literate individual can make informed decisions, distinguish between needs and wants, and avoid unnecessary financial risks. Although students learn mathematics and economics in school, these subjects do not always equip them with practical financial skills. Knowing how to calculate percentages is different from understanding how interest accumulates on a loan or how to prepare a monthly budget. Financial education bridges this gap between theoretical knowledge and practical application.
One of the greatest advantages of teaching financial literacy at an early age is the development of responsible money-management habits. Students who understand the importance of saving can learn to set financial goals, control unnecessary spending, and plan for future needs. For instance, a student receiving pocket money can learn to divide it between essential expenses, personal interests, and savings. Such simple exercises encourage discipline and decision-making. These habits, when developed during childhood, can help individuals avoid financial difficulties and become more independent in adulthood.
As digital transactions, online shopping, and mobile banking become increasingly common, young people are exposed to various financial risks. Online scams, fraudulent investment schemes, phishing messages, and identity theft can affect individuals who lack financial awareness. Financial literacy can help students recognise suspicious offers, protect confidential banking information, and understand the importance of secure digital transactions. They can also learn why sharing passwords, personal identification numbers (PINs), and one-time passwords (OTPs) with unknown persons is dangerous. In this way, financial education becomes more than a money-management skill; it becomes an essential tool for personal security in the digital age.
Financial literacy can also contribute to a more inclusive society. Students from different economic backgrounds do not always have equal access to financial guidance at home. Schools can provide a common platform where every student learns the fundamentals of managing money. This knowledge is particularly valuable for young people who may become the first members of their families to pursue higher education or professional careers. Understanding banking, savings, credit, and financial planning can help them make better decisions and reduce their dependence on others. Furthermore, financial literacy can encourage entrepreneurship by teaching students how to estimate costs, manage resources, assess risks, and plan business activities.
Financial education need not become a complicated or excessively theoretical subject. Schools can introduce it through practical activities, classroom discussions, budgeting exercises, simulated banking activities, and age-appropriate case studies. Students can learn about household budgets, the difference between debit and credit, the consequences of borrowing, the importance of emergency savings, and the basics of taxation. Teachers can also explain responsible digital payment practices and introduce the fundamentals of investment without encouraging speculative behaviour. Such an approach would make financial education engaging, practical, and relevant to everyday life.
Financial literacy is not merely a skill for managing money; it is a foundation for responsible decision-making and long-term security. Academic qualifications may open doors to professional opportunities, but financial knowledge helps individuals manage the opportunities they receive. Schools must therefore recognise financial literacy as an essential life skill rather than an optional area of learning. By educating children about money before they begin earning it, we can prepare a generation that is more confident, independent, and financially responsible. After all, true education should not only teach students how to earn a living but also how to manage it wisely.